 Oct-12-2026
Mutual funds have become a popular investment option among Indian investors. They provide access to different financial markets, offer various investment strategies and allow individuals to invest according to their financial goals.
Yet many people hesitate to invest because of misconceptions about how mutual funds work.
Some believe that mutual funds require a large amount of money. Others assume that opening a Demat account is compulsory or that their money will remain locked in for several years.
These assumptions can prevent investors from exploring investment options that may suit their requirements.
The reality is that mutual funds come in different categories, each with its own investment objective, risk level, liquidity characteristics and recommended investment horizon.
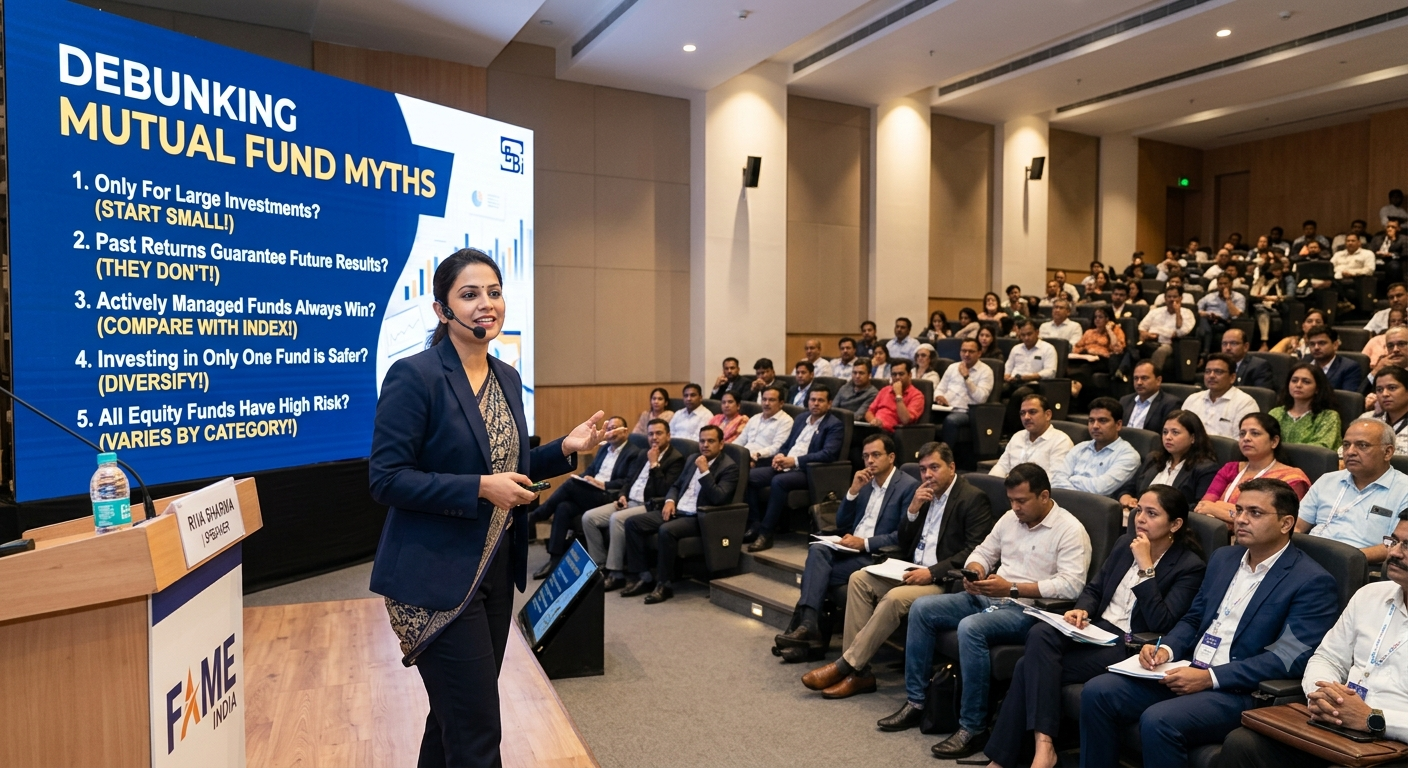
Let's examine five common mutual fund myths and understand the facts behind them.
A mutual fund is an investment vehicle that pools money from multiple investors and invests it in financial instruments according to a defined investment objective.
Depending on the scheme, these investments may include:
Equity shares
Government securities
Corporate bonds
Money-market instruments
Gold-related instruments
Other permitted assets
Investors receive units of the mutual fund in proportion to their investment and the applicable Net Asset Value (NAV).
The value of these units changes according to the performance of the underlying portfolio.
Mutual funds may offer diversification and professional management, but they remain subject to investment risks.
Many first-time investors believe mutual funds are suitable only for people with substantial savings.
They assume that investing requires ₹50,000, ₹1 lakh or an even larger amount.
This is not necessarily true.
Many mutual fund schemes allow investors to begin with relatively small amounts.
The minimum investment depends on the scheme and the investment method.
Some schemes permit systematic investments starting at a few hundred rupees, while certain options may allow even smaller contributions.
This makes mutual funds accessible to investors with different income levels.
Suppose an investor begins a monthly SIP of ₹1,000.
The total amount invested would be:
| Investment Period | Total Contribution |
|---|---|
| 1 year | ₹12,000 |
| 3 years | ₹36,000 |
| 5 years | ₹60,000 |
| 10 years | ₹1,20,000 |
| 15 years | ₹1,80,000 |
These figures represent contributions only, not investment returns.
The actual investment value will depend on market performance, scheme expenses and other applicable factors.
A small SIP may help investors develop a regular saving and investing habit without committing a large amount upfront.
Investors may also increase their SIP contribution as their income and financial capacity grow.
The important factor is not necessarily the size of the first investment, but whether the investment plan is suitable and sustainable.
Reality: You do not need to be wealthy to begin investing in mutual funds.
Some investors believe opening a mutual fund account involves extensive paperwork, repeated visits and complicated procedures.
This concern can discourage people from getting started.
Mutual fund investing has become more accessible through digital platforms and electronic verification processes.
Investors generally need to complete the applicable Know Your Customer (KYC) requirements.
Depending on the investor's circumstances and verification method, the process may involve:
PAN details
Identity verification
Address verification
Bank account information
Photograph or video verification where applicable
Other regulatory declarations
KYC can often be completed digitally through an authorised intermediary.
However, additional verification or KYC updates may be required in certain circumstances.
KYC helps financial institutions verify investor identities and comply with regulatory requirements.
It is designed to support:
Investor identification
Prevention of financial fraud
Anti-money-laundering compliance
Accurate investor records
Secure financial transactions
Not necessarily.
Once KYC is properly completed and validated, the information can generally be used across eligible intermediaries, subject to the prevailing KYC status and regulatory requirements.
However, changes in personal details, incomplete records or verification requirements may result in additional documentation.
Reality: Mutual fund documentation is generally manageable, and digital processes have made investing more convenient.
Many investors assume that because mutual funds invest in the stock market, they must open a Demat account before purchasing mutual fund units.
This is a common misconception.
A Demat account is not compulsory for investing in many conventional mutual fund schemes.
Investors can generally hold mutual fund units in a non-Demat format through the relevant mutual fund folio.
Alternatively, eligible mutual fund units may be held in Demat form.
The available holding method depends on the product and transaction platform.
| Basis | Mutual Fund Folio | Demat Account |
|---|---|---|
| Purpose | Records mutual fund holdings | Holds eligible securities electronically |
| Mandatory for conventional mutual funds | No Demat account required | Generally optional |
| Holding format | Statement of account | Dematerialised units |
| Account provider | AMC or registrar records | Depository participant |
| Use for listed shares | Not applicable | Generally required |
| Applicable charges | Depend on scheme and platform | DP charges may apply |
Suppose an investor wants to start a SIP in an open-ended equity mutual fund.
The investor may be able to complete KYC, register the required bank details and invest through the mutual fund's permitted non-Demat process.
Opening a separate Demat account is not necessarily required.
However, products such as exchange-traded funds (ETFs), which are bought and sold on stock exchanges, generally require a trading and Demat arrangement for ordinary exchange-based transactions.
Reality: A Demat account is optional for many conventional mutual funds, but it may be required for certain exchange-traded investment products.
Some investors believe that once money is invested in a mutual fund, it cannot be withdrawn for several years.
They may therefore avoid mutual funds because they are concerned about accessing their savings.
Not all mutual funds have mandatory lock-in periods.
Many open-ended mutual fund schemes allow investors to redeem units on eligible business days, subject to applicable rules.
However, liquidity depends on the scheme category and its terms.
Open-ended mutual funds generally permit subscriptions and redemptions on an ongoing basis.
Investors can submit redemption requests according to the scheme's procedures.
The applicable NAV and redemption payment timeline depend on the relevant rules.
Equity Linked Savings Schemes (ELSS) have a statutory lock-in period of three years.
Each investment, including each SIP instalment, has its own three-year lock-in period.
The availability of tax benefits depends on the investor's applicable tax regime and current income-tax provisions.
Close-ended schemes generally have a specified maturity period.
Exit options depend on the scheme structure, including any exchange listing and available market liquidity.
These are different concepts.
Lock-in period: A restriction on redemption during a specified period.
Exit load: A charge that may apply when units are redeemed within a specified period.
A mutual fund can have no lock-in period but still impose an exit load for early redemption.
In many open-ended schemes, investors can request cancellation of future SIP instalments according to the applicable procedure and processing timelines.
However, stopping a SIP does not automatically redeem units already purchased.
Existing units remain invested unless separately redeemed, subject to applicable restrictions.
Reality: Many mutual funds provide redemption flexibility, but investors should check lock-ins, exit loads and settlement timelines before investing.
Many people associate mutual funds exclusively with long-term wealth creation.
They assume that every mutual fund investment must be held for at least five or ten years.
Different mutual fund categories are designed for different investment objectives and time horizons.
While equity-oriented mutual funds are generally more appropriate for longer investment horizons because of their market volatility, certain debt and money-market-oriented schemes may be considered for shorter periods.
The appropriate choice depends on the investor's requirements and the specific scheme's risks.
| Investment Horizon | Categories Investors May Evaluate | Important Consideration |
|---|---|---|
| Very short term | Overnight or liquid funds | Liquidity, credit and interest-rate risks |
| Short term | Suitable short-duration debt categories | Portfolio quality and duration risk |
| Medium term | Selected debt or hybrid categories | Volatility and asset allocation |
| Long term | Diversified equity funds | Market volatility and long-term growth potential |
This table is illustrative, not a universal suitability recommendation.
Equity markets can experience significant short-term price fluctuations.
A longer investment horizon may give investors more time to experience different market cycles, although it does not eliminate the possibility of losses.
For example, an equity mutual fund may experience a substantial decline during a market correction.
An investor who needs the money immediately may be forced to redeem at an unfavourable value.
This is why investment horizon matters.
No.
Even debt-oriented mutual funds can face risks such as:
Interest-rate changes
Credit deterioration
Liquidity constraints
Changes in market yields
Valuation fluctuations
The risk level depends on the securities held and the scheme's investment strategy.
Reality: Mutual funds are available for different investment horizons, but the scheme must match the investor's objective and risk capacity.
| Common Myth | Actual Fact |
|---|---|
| Mutual funds require large investments | Many schemes allow relatively small investments |
| KYC and documentation are too complicated | Digital onboarding and KYC processes are widely available |
| A Demat account is always required | Many conventional mutual funds can be held without one |
| Every mutual fund has a lock-in period | Many open-ended schemes permit redemption, subject to terms |
| Mutual funds are only for long-term goals | Different categories serve different investment horizons |
Apart from these five common myths, several other assumptions can influence investment decisions.
Mutual fund returns are generally market-linked.
Equity funds depend heavily on stock-market performance, while debt funds are influenced by interest rates, credit conditions and other factors.
Investors should not assume that a mutual fund will deliver a fixed annual return.
Suppose two mutual funds have the following NAVs:
Fund A: ₹20
Fund B: ₹200
The lower NAV does not automatically make Fund A a better or cheaper investment.
NAV represents the per-unit value of the fund's net assets.
The quality of the underlying portfolio, investment strategy, costs and suitability are more meaningful than the absolute NAV.
Fund ratings are generally based on historical measures and specific methodologies.
A high rating may be useful as an initial screening input, but it does not guarantee future performance.
Investors should also review risk, costs, portfolio characteristics and consistency.
A SIP is an investment method, not a guarantee of positive returns.
Regular investing may help reduce dependence on choosing a single entry date, but it cannot eliminate market risk.
If the underlying fund performs poorly, a SIP investment can also lose value.
After understanding these myths, the next step is to evaluate schemes according to your financial requirements.
Determine whether you are investing for retirement, education, a planned expense or general wealth creation.
The time available before you need the money influences the type of investment risk you can reasonably consider.
An investor who cannot tolerate significant volatility should not select an equity-heavy portfolio merely because recent returns look attractive.
Compare schemes with similar investment objectives rather than comparing unrelated categories solely on past returns.
Fund expenses reduce the returns available to investors.
Compare costs while also considering investment strategy, tracking quality where relevant and other characteristics.
For equity funds, consider diversification, sector exposure and concentration.
For debt funds, review credit quality, duration and liquidity characteristics.
Check whether the scheme has:
A lock-in period
Exit load
Redemption restrictions
Applicable payout timelines
The scheme Riskometer can help investors understand its disclosed risk classification, but it should be considered alongside the full scheme information.
Suppose an investor decides to invest ₹2,000 per month through a SIP.
Over ten years, the total contribution would be:
₹2,000 × 12 × 10 = ₹2,40,000
The final value may be higher or lower than the amount invested depending on the scheme's performance and applicable costs.
The example demonstrates how regular contributions can build an investment corpus over time, but it does not imply any guaranteed outcome.
Even after understanding the basic facts, investors should avoid:
Selecting funds only on recent returns
Assuming every mutual fund is low-risk
Ignoring expense ratios
Investing without a defined goal
Choosing unsuitable categories for short-term needs
Holding multiple funds with substantially overlapping portfolios
Redeeming solely because of short-term volatility
Ignoring exit loads and lock-in conditions
Assuming SIPs eliminate investment risk
Investing without reading the scheme's key information
A clear investment plan is more useful than relying on popular assumptions.
Mutual fund investing is often misunderstood because investors receive incomplete or outdated information about how the products work.
The belief that mutual funds require large investments, complicated paperwork, compulsory Demat accounts, long lock-in periods or exclusively long-term commitments does not accurately describe the full range of available schemes.
In reality, mutual funds offer different investment methods, portfolio strategies and liquidity characteristics.
However, convenience and accessibility should not be confused with guaranteed safety or returns.
Before investing, understand the scheme's objective, underlying assets, risk level, costs, investment horizon and redemption conditions.
Making investment decisions based on these factors is far more useful than relying on common mutual fund myths.
Common myths include the belief that mutual funds require large investments, involve complicated documentation, always need a Demat account, have compulsory lock-in periods and are suitable only for long-term investors.
Many mutual fund schemes permit relatively small investments, including SIPs of ₹500 or less in some cases. The minimum amount depends on the particular scheme.
Yes, investors generally need to comply with applicable KYC requirements before investing in mutual funds.
A Demat account is not compulsory for many conventional mutual fund schemes. Investors can generally hold units in a non-Demat folio format.
No. Mutual funds are exposed to risks associated with their underlying investments, including market, credit, interest-rate and liquidity risks.
No. Many open-ended mutual funds allow redemption according to scheme terms. Certain products, such as ELSS, have mandatory lock-in periods.
ELSS investments have a three-year lock-in period. Each SIP instalment is subject to its own three-year lock-in.
Many open-ended mutual funds permit redemption on eligible business days, but the applicable NAV, exit load, restrictions and payment timeline depend on the scheme.
Certain categories may be evaluated for shorter investment horizons, but suitability depends on liquidity requirements, credit quality, interest-rate risk and the investor's financial circumstances.
No. SIP is a systematic investment method and does not guarantee profits or protect against market losses.
Not necessarily. A lower NAV does not indicate that a scheme is undervalued or offers better returns.
Beginners should first identify their goals, investment horizon and risk tolerance, then compare suitable schemes based on strategy, diversification, costs, liquidity and risk disclosures.
What are the five common myths about mutual funds?
Do mutual funds require a large initial investment?
Can I invest ₹500 in mutual funds?
Is KYC compulsory for mutual fund investments?
Is a Demat account necessary for mutual funds?
Do all mutual funds have a lock-in period?
Can mutual funds be redeemed before three years?
Are mutual funds suitable for short-term investment?
Does a SIP guarantee returns?
Are mutual funds safe for beginners?
Is a lower mutual fund NAV better?
How can investors choose a suitable mutual fund?