 Oct-19-2026
In intraday trading, identifying the right entry point is only one part of the trading process. Knowing when to exit is equally important.
A trader may correctly identify a stock's price direction but still suffer a loss by holding the position for too long. Similarly, exiting a trade too early may prevent the trader from benefiting from a favourable price movement.
This is why having a clearly defined intraday trading exit strategy matters.
An exit strategy helps traders decide when to book profits, limit losses or close a position when market conditions change.
Instead of relying entirely on emotions, traders can use predefined price levels, technical indicators, risk-reward calculations and time-based rules.
However, no exit strategy guarantees profits or prevents all losses. Market volatility, liquidity conditions and execution delays can affect the actual exit price.
Let's understand the commonly used exit strategies for day traders and how they work.
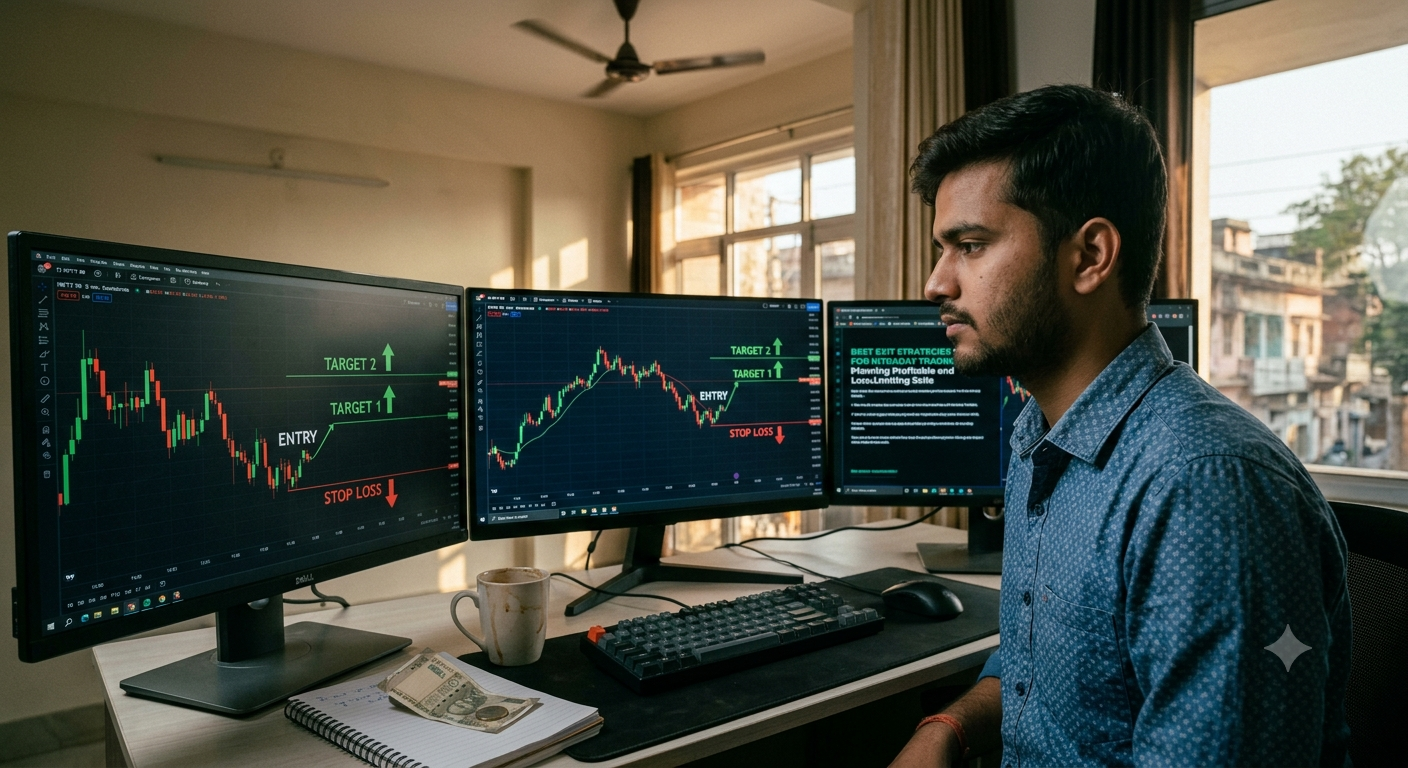
An exit strategy is a predetermined plan that defines when and how a trader will close an open position.
For example, suppose a trader purchases 100 shares at ₹500 each.
Before entering the trade, the trader decides:
Entry price: ₹500
Profit target: ₹515
Stop-loss level: ₹492
The trader now has a defined plan for both favourable and unfavourable price movements.
If the stock rises towards ₹515, the trader may exit according to the profit-taking plan.
If the stock falls towards ₹492, the trader may exit to limit the loss.
The important point is that the exit levels are determined through analysis rather than decided impulsively during the trade.
Intraday trading involves buying and selling securities within the same trading session.
Prices can change rapidly because of:
Market news
Economic announcements
Corporate developments
Institutional trading activity
Changes in liquidity
Market volatility
Sudden shifts in investor sentiment
Without a defined exit strategy, traders may hold losing positions hoping for a recovery or continue holding profitable positions until the gains disappear.
A structured exit plan can help traders:
Define acceptable risk before entering a trade.
Establish realistic profit-taking levels.
Reduce emotional decision-making.
Maintain consistency in trading decisions.
Manage exposure during volatile conditions.
Evaluate trading performance more objectively.
The risk-reward ratio is one of the most commonly used concepts in trading risk management.
It compares the potential loss on a trade with its potential profit.
Before entering a trade, traders can evaluate whether the expected reward reasonably compensates for the amount being risked.
Risk-Reward Ratio = Potential Loss ÷ Potential Profit
Alternatively, traders may express the same relationship as a reward-to-risk ratio.
Suppose a trader plans the following transaction:
Entry price: ₹250
Stop-loss: ₹245
Profit target: ₹265
Potential risk per share:
₹250 − ₹245 = ₹5
Potential reward per share:
₹265 − ₹250 = ₹15
Risk-reward ratio:
₹5 : ₹15 = 1:3
The trader is targeting ₹3 of potential profit for every ₹1 of planned risk.
However, this does not mean the trade has a high probability of success.
A favourable ratio is useful only when the target and stop-loss levels are supported by realistic market analysis.
| Risk-Reward Ratio | Risk | Potential Reward |
|---|---|---|
| 1:1 | ₹1,000 | ₹1,000 |
| 1:1.5 | ₹1,000 | ₹1,500 |
| 1:2 | ₹1,000 | ₹2,000 |
| 1:3 | ₹1,000 | ₹3,000 |
These are illustrative values, not guaranteed trading outcomes.
A stop-loss is a predefined price level at which a trader intends to close a position if the market moves against the trade.
Its primary purpose is to manage downside risk.
Suppose a trader buys 200 shares at ₹400.
The trader places a stop-loss trigger at ₹392.
Planned loss per share:
₹400 − ₹392 = ₹8
Planned loss for 200 shares:
₹8 × 200 = ₹1,600
The trader has defined an intended loss limit before entering the position.
However, a stop-loss trigger does not guarantee execution at exactly ₹392. Depending on the order type, market liquidity and price movement, the actual exit may occur at a different price or the order may remain unexecuted.
Establishes a predefined risk level.
Helps reduce impulsive decision-making.
Supports disciplined position sizing.
Can reduce the tendency to hold losing trades indefinitely.
Sudden price gaps may cause slippage.
Stop-loss orders may be triggered by short-term volatility.
Execution depends on the order type and available liquidity.
A trailing stop-loss is designed to adjust the exit level as the market moves favourably.
Unlike a fixed stop-loss, a trailing stop can help protect part of an unrealised gain while allowing the position to remain open.
Suppose a trader buys a stock at ₹500.
Initial stop-loss: ₹490
The share price then rises to ₹520.
The trader raises the stop-loss to ₹510.
Later, the stock rises to ₹535.
The trader moves the stop-loss to ₹525.
| Share Price | Illustrative Stop-Loss |
|---|---|
| ₹500 | ₹490 |
| ₹520 | ₹510 |
| ₹535 | ₹525 |
If the price subsequently reverses, the stop-loss may be triggered.
For a long position, a conventional trailing stop is generally moved upwards as the trade progresses, rather than lowered to increase risk.
A trailing stop may be considered when a stock is moving in a sustained intraday trend.
It allows traders to follow favourable price movements without needing to predict the exact top.
However, a trailing stop set too close to the market price may result in an early exit during ordinary price fluctuations.
A fixed profit target involves closing a position when the price reaches a predetermined level.
The target may be based on:
Support and resistance
Previous price highs or lows
Chart patterns
Volatility
Risk-reward calculations
Technical analysis
A trader buys shares at ₹750.
Based on chart analysis, the trader identifies a resistance zone around ₹775.
The trader may set a profit-taking level near that area.
If the price reaches the target and the exit order executes, the trader books the resulting gain.
The benefit of a fixed target is clarity.
However, the market may reverse before reaching the target or continue moving favourably after the position is closed.
Support and resistance are price zones where buying or selling activity has previously influenced market movements.
Traders often use these levels to plan exits.
Suppose a stock is trading at ₹310.
Technical analysis identifies a resistance zone around ₹325.
A trader holding a long position may consider booking profits near that zone if the price approaches it.
Suppose a trader has a short intraday position entered at ₹600.
A support zone is identified around ₹580.
The trader may consider covering the position near that area.
Support and resistance are not guaranteed turning points.
Prices can break through these levels, especially during periods of high volatility or strong momentum.
Traders should therefore consider confirmation, liquidity and their broader risk-management plan.
A time-based exit closes a position after a predefined period or at a specified time, regardless of whether the original profit target has been reached.
This strategy can be useful when traders want to avoid holding positions during uncertain or highly volatile periods.
A trader enters a position at 10:30 AM.
The trading plan states that the position will be closed if the expected price movement has not developed within 45 minutes.
If the stock remains range-bound, the trader exits instead of waiting indefinitely.
Traders may consider exiting:
Before a scheduled economic announcement.
Before an important company announcement, where the timing is known.
When their planned trading window ends.
Before the broker's intraday square-off deadline.
When the original setup has failed to develop within the expected period.
The exact exit timing should reflect the trading strategy and applicable exchange and broker rules.
Volume Weighted Average Price (VWAP) is a commonly used intraday indicator that combines price and trading volume.
It represents the volume-weighted average traded price over the relevant calculation period, commonly the current session.
Traders may use VWAP as a reference for assessing intraday price behaviour.
Suppose a trader enters a long position while a stock is trading above VWAP.
If the stock later moves below VWAP and fails to recover, the trader may interpret this as a sign of weakening intraday strength.
Depending on the trading plan, this may provide a reason to reduce or close the position.
VWAP is not a guaranteed support or resistance level.
A stock can cross above and below VWAP repeatedly during a sideways market, generating misleading signals.
VWAP is therefore often considered alongside price action, volume and other market information.
Moving averages help traders identify the general direction of price movements.
Common intraday chart settings may include short-period exponential moving averages, such as 9 EMA or 20 EMA.
These are examples, not universally optimal settings.
A trader enters a long position during an upward trend.
The stock continues trading above a selected moving average.
If the price subsequently closes below that average, the trader may evaluate whether the trend is weakening.
The exit decision can depend on whether the move is confirmed by other signals.
Provides a systematic trend reference.
Can help traders remain in a developing trend.
May reduce reliance on subjective price predictions.
Moving averages are lagging indicators.
During sideways conditions, repeated crossovers may cause frequent exits and re-entries.
Average True Range (ATR) is a technical indicator used to estimate price volatility.
It measures the average range of price movements over a selected number of periods.
ATR does not predict whether a stock will rise or fall.
Instead, it can help traders understand how widely prices are moving.
Suppose:
Entry price: ₹1,000
ATR: ₹12
Illustrative stop distance: 1.5 × ATR
Stop distance:
₹12 × 1.5 = ₹18
For a long position, an illustrative stop level would be:
₹1,000 − ₹18 = ₹982
The selected ATR multiple should reflect the trading system and market conditions.
A fixed ₹5 stop-loss may be too tight for a highly volatile stock but relatively wide for a low-volatility stock.
ATR can help traders adjust planned exit distances to prevailing volatility.
However, volatility-adjusted stops can still be triggered during unexpected price movements.
Partial profit booking involves closing a portion of an open position while allowing the remaining quantity to continue.
This approach may help traders balance realised gains with the possibility of further favourable movement.
Suppose a trader buys 400 shares at ₹200.
The price rises to ₹210.
The trader sells 200 shares.
Gross realised gain:
200 × ₹10 = ₹2,000
The remaining 200 shares continue to be held according to the trading plan.
The trader may use a trailing stop or another predefined exit rule for the remaining quantity.
Allows some profit to be realised.
Reduces the remaining position size.
Can provide flexibility during trending markets.
May reduce total profit if the price continues rising strongly.
Additional transactions may increase costs.
The remaining position still carries market risk.
| Exit Strategy | Main Purpose | Important Limitation |
|---|---|---|
| Risk-reward ratio | Compare planned gain and loss | Does not indicate success probability |
| Fixed stop-loss | Define intended downside limit | Slippage and execution risk |
| Trailing stop-loss | Follow favourable price movements | Can exit during temporary pullbacks |
| Fixed profit target | Book gains at a planned level | May exit before a larger move |
| Support and resistance | Use important price zones | Levels can break |
| Time-based exit | Limit exposure duration | May close a developing trade early |
| VWAP-based exit | Evaluate intraday price strength | Can produce false signals |
| Moving average exit | Follow trend changes | Lagging signals |
| ATR-based exit | Adjust stops for volatility | Cannot prevent unexpected losses |
| Partial profit booking | Reduce exposure while retaining participation | May reduce gains during strong trends |
An exit strategy is incomplete without position sizing.
Position sizing determines how many shares a trader plans to buy or sell based on the amount of capital they are prepared to risk.
Position Size = Maximum Planned Risk ÷ Risk Per Share
Suppose:
Trading capital: ₹1,00,000
Maximum planned risk per trade: 1%
Entry price: ₹250
Stop-loss: ₹245
Maximum planned risk:
₹1,00,000 × 1% = ₹1,000
Risk per share:
₹250 − ₹245 = ₹5
Illustrative position size:
₹1,000 ÷ ₹5 = 200 shares
The position would have a market value of ₹50,000.
The trader should also verify available funds, applicable margins and other requirements.
This calculation sets an intended risk budget, not a guaranteed maximum loss. Slippage, gaps, execution failures and transaction costs can cause the actual loss to exceed ₹1,000.
Suppose a trader identifies an opportunity in a stock.
The trading plan is:
| Particulars | Value |
|---|---|
| Entry price | ₹500 |
| Stop-loss | ₹490 |
| Profit target | ₹520 |
| Quantity | 100 shares |
| Planned risk per share | ₹10 |
| Planned reward per share | ₹20 |
| Risk-reward ratio | 1:2 |
| Planned total risk | ₹1,000 |
| Planned gross profit | ₹2,000 |
The trader now has clear reference levels.
If the stock reaches ₹520 and the sell order executes at that price:
Gross profit:
₹20 × 100 = ₹2,000
If the exit executes at ₹490:
Gross loss:
₹10 × 100 = ₹1,000
Suppose the stock reaches ₹515 but begins weakening.
If the trader's predefined strategy allows trailing the stop-loss, the exit level may be adjusted to manage the remaining risk.
Actual results depend on execution prices and applicable costs.
A high percentage of winning trades does not automatically mean a trading strategy is profitable.
Average profit and average loss also matter.
Consider two hypothetical strategies.
| Metric | Strategy A | Strategy B |
|---|---|---|
| Win rate | 70% | 40% |
| Average winning trade | ₹500 | ₹1,500 |
| Average losing trade | ₹1,500 | ₹700 |
For Strategy A, the expected gross outcome per trade is:
(70% × ₹500) − (30% × ₹1,500)
= −₹100
For Strategy B:
(40% × ₹1,500) − (60% × ₹700)
= ₹180
These hypothetical calculations show that the relationship between winning trades, losing trades and their respective sizes matters.
Both results are before brokerage, taxes, slippage and other costs. Actual future results may differ significantly.
Increasing the allowed loss simply because the market is moving against the position can undermine the original risk plan.
A trader may refuse to exit because accepting a loss feels uncomfortable.
This can allow a manageable loss to become much larger.
Exiting every profitable position immediately may prevent a strategy from achieving its intended reward-to-risk characteristics.
A small gross profit can become substantially smaller after brokerage, statutory charges and slippage.
Targets should be based on market structure and volatility rather than arbitrary expectations.
Entering a position without knowing where to exit can create unnecessary uncertainty.
Trying to recover a loss immediately can lead to impulsive trades and greater exposure.
A stop-loss may not execute at the expected price when liquidity is insufficient.
Understanding order execution is essential.
A stop-loss order can be implemented using different order types, subject to exchange, segment and broker availability.
A stop-loss market order, where permitted, generally becomes a market order once the trigger condition is met. Execution may occur at a different price from the trigger.
A stop-loss limit order becomes a limit order after triggering. It provides a limit-price condition but may remain unexecuted if the market moves beyond the specified limit.
Traders should understand the permitted order types for their segment before relying on a particular exit mechanism.
The appropriate exit strategy depends on several factors.
A trader using a short-duration scalping approach may require different exit rules from a trader following an intraday trend.
Highly volatile markets may require different stop distances and position sizes.
Stocks with low trading volume may experience greater execution difficulty.
The maximum acceptable planned loss should be determined before entering a position.
Trending and range-bound markets may require different exit techniques.
Strategies involving frequent exits and re-entries must account for cumulative transaction costs.
Before placing a trade, consider the following:
What is the reason for entering the trade?
Where is the planned entry price?
What market movement would invalidate the setup?
Where should the stop-loss be placed?
What is the realistic profit target?
What is the risk-reward ratio?
How many shares can be traded within the risk budget?
Is the stock sufficiently liquid?
Are major announcements expected?
What is the time-based exit rule?
What are the applicable trading costs?
What happens if the order does not execute as expected?
A well-planned exit strategy is an important part of intraday trading.
While traders often spend considerable time identifying entry opportunities, the eventual outcome also depends on how positions are managed and closed.
Techniques such as fixed stop-losses, trailing stop-losses, realistic profit targets, risk-reward analysis, time-based exits and volatility-based methods can provide structure to trading decisions.
However, none of these methods can eliminate market risk or guarantee successful execution.
A trader should evaluate exit levels alongside position size, liquidity, volatility, costs and overall risk capacity.
The objective of an exit strategy is not to predict every market movement correctly. It is to establish a consistent framework for managing trades when prices move either favourably or unfavourably.
An exit strategy is a predefined plan for closing a trading position based on price targets, stop-loss levels, technical signals, time limits or other conditions.
There is no universally best exit strategy. The appropriate method depends on the trading setup, volatility, liquidity, risk capacity and market conditions.
A stop-loss is a predefined price level intended to limit losses when the market moves against a position. Actual execution may differ from the trigger price.
A trailing stop-loss adjusts the planned exit level as the market moves favourably, allowing traders to manage risk while potentially remaining in a trend.
Traders often evaluate ratios such as 1:2 or 1:3, but a favourable ratio alone does not guarantee profitability. The probability of reaching the target, execution costs and loss frequency also matter.
Predefined risk controls are important in intraday trading. Stop-loss orders are one commonly used tool, although they cannot guarantee a specific exit price or eliminate losses.
Yes. Some traders use VWAP as a reference for assessing intraday price strength or weakness. It should not be treated as a guaranteed reversal level.
A time-based exit closes a position after a specified duration or at a predefined time, even if the original target has not been reached.
Partial profit booking can reduce exposure while allowing part of the position to remain open. However, it may reduce gains if the price continues moving favourably.
A basic risk-based method divides the maximum planned loss by the planned risk per share, subject to available capital, margins and other constraints.
Yes. Stop-loss orders may experience slippage, remain unexecuted or execute at unexpected prices depending on the order type, market conditions and liquidity.
An exit strategy helps beginners establish risk limits and profit-taking rules before entering a trade, reducing dependence on impulsive decisions.
What are the best exit strategies for intraday trading?
How do day traders decide when to exit?
What is a stop-loss exit strategy?
How does a trailing stop-loss work?
What is the ideal risk-reward ratio for day trading?
How can support and resistance be used for exits?
What is a time-based exit in intraday trading?
Can VWAP help identify intraday exit points?
What is an ATR-based stop-loss?
How do traders calculate position size?
What is partial profit booking?
Can a stop-loss guarantee protection from losses?