 Oct-26-2026
Retirement is an important financial milestone. While regular employment or business income may eventually stop, household expenses, healthcare requirements and lifestyle needs continue.
This is why retirement planning should begin well before a person stops working.
A well-structured retirement plan helps individuals accumulate savings during their earning years and manage those savings after retirement.
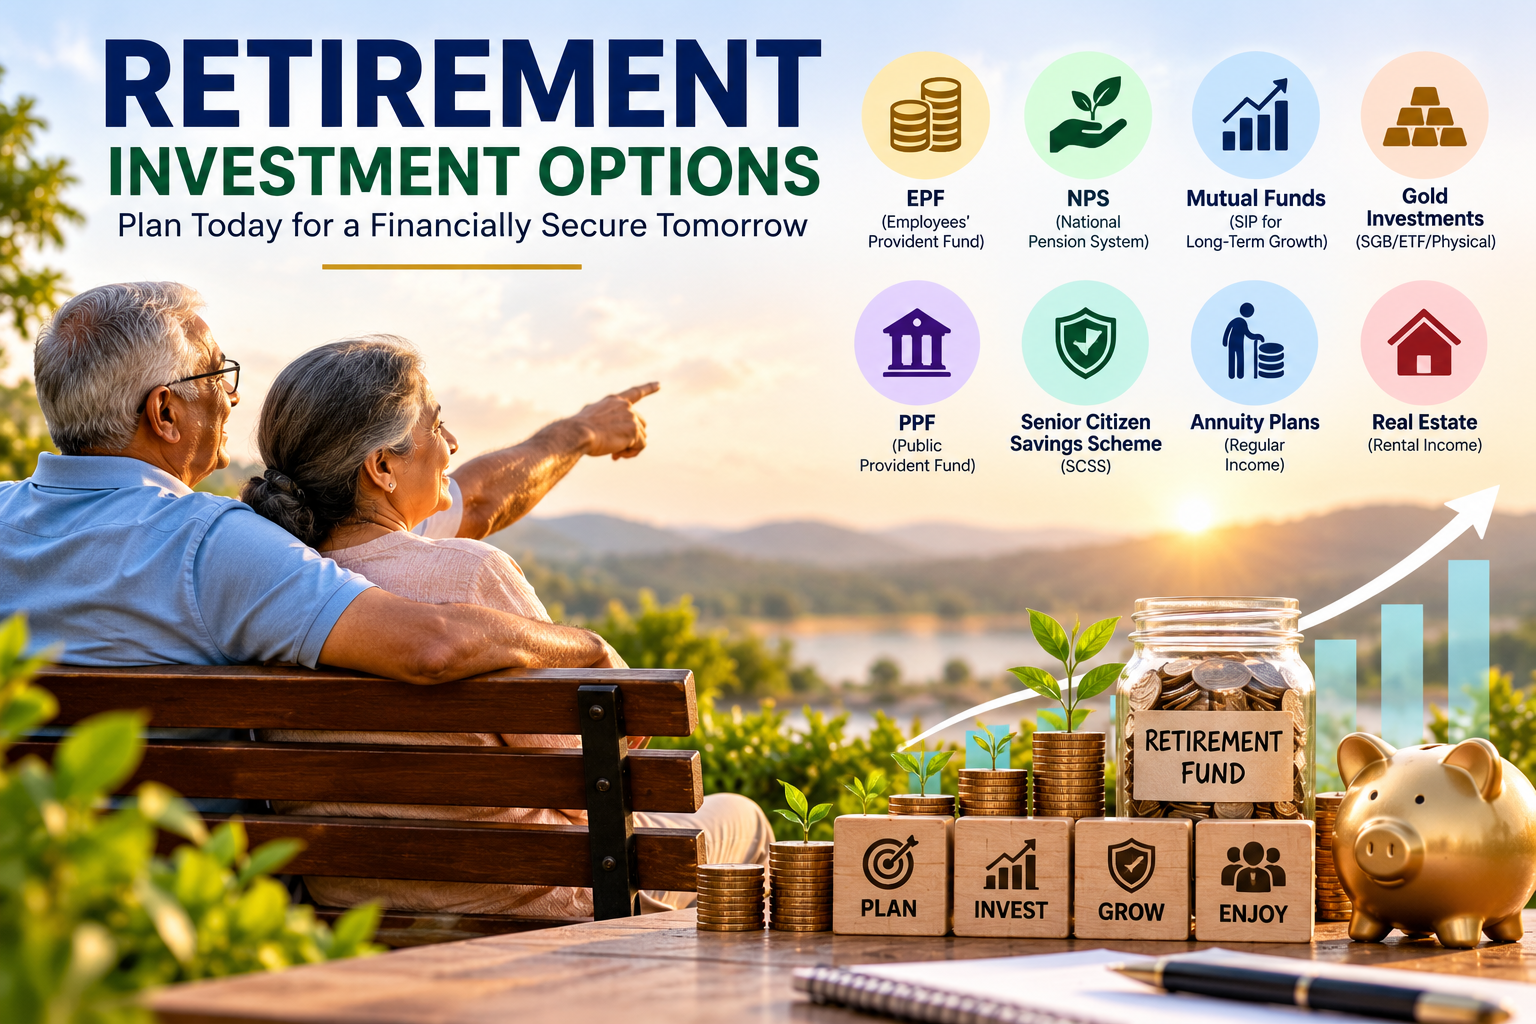
India offers several retirement investment options, including the Employees' Provident Fund (EPF), Public Provident Fund (PPF), National Pension System (NPS), mutual funds, fixed deposits, Senior Citizens' Savings Scheme (SCSS) and annuity products.
Each option has different characteristics relating to returns, risk, liquidity, taxation and investment duration.
Understanding these differences can help investors create a retirement portfolio aligned with their financial goals.
Retirement investment options are financial products or strategies used to accumulate and manage money for the years after regular employment or business income ends.
They generally serve two purposes:
Wealth accumulation: Building a retirement corpus during working years.
Retirement income: Using the accumulated corpus to meet living expenses after retirement.
For example, an individual may invest regularly in EPF, NPS or mutual funds during employment.
After retirement, the person may use a combination of deposits, eligible government savings schemes, annuities and planned withdrawals to support regular expenses.
The appropriate combination depends on age, income, financial responsibilities, risk tolerance and expected retirement duration.
After retirement, salary or business income may reduce significantly or stop entirely.
A retirement corpus can help replace part of that income.
The purchasing power of money declines when prices rise.
An amount sufficient for household expenses today may be inadequate 20 or 30 years later.
Medical treatment, medicines, insurance premiums and long-term care can become significant expenses during retirement.
Someone retiring at 60 may need to fund expenses for 25 years or longer.
Planning for longevity helps reduce the risk of exhausting savings too early.
Retirement savings can reduce dependence on family members and provide greater flexibility in managing everyday expenses.
The Employees' Provident Fund is a retirement savings arrangement available to eligible salaried employees.
Contributions are generally made by employees and employers according to applicable rules.
The accumulated amount earns interest at the rate notified for the relevant period.
Designed primarily for retirement savings.
Regular contributions support disciplined accumulation.
Employer contributions can supplement employee savings.
Interest is credited according to applicable rules.
Withdrawals and advances are governed by prescribed conditions.
Tax treatment depends on eligibility, contribution limits and prevailing law.
EPF can help salaried individuals build retirement savings systematically without requiring frequent investment decisions.
It is not a fully flexible savings account. Withdrawal rules, employment status and other conditions may affect access to funds.
The Public Provident Fund is a government-backed long-term savings scheme.
It can be considered by eligible individuals who want a relatively stable component within their long-term savings plan.
Initial tenure of 15 years.
Extension options available according to scheme rules.
Government-notified interest rate, subject to periodic revision.
Contributions are subject to prescribed minimum and maximum limits.
Partial withdrawal and loan facilities are governed by applicable conditions.
Tax benefits are subject to prevailing rules.
Suppose an individual contributes ₹60,000 annually to a PPF account.
Over 15 years, total contributions would be:
₹60,000 × 15 = ₹9,00,000
The final maturity value would also include applicable interest, subject to the timing of contributions and rates prevailing during the period.
PPF offers a structured savings mechanism with government backing.
Its long tenure and withdrawal restrictions make it less suitable for money that may be required at short notice.
The National Pension System is a retirement-oriented investment framework regulated by the Pension Fund Regulatory and Development Authority (PFRDA).
It allows eligible subscribers to build retirement savings through contributions invested according to the applicable pension investment framework.
NPS investments are market-linked, so returns are not guaranteed.
A subscriber contributes money during the accumulation phase.
The contributions are invested according to the selected pension fund and asset-allocation arrangement.
The retirement corpus depends on contributions, investment performance, expenses and applicable rules.
At exit, the amount available for lump-sum withdrawal and any annuity requirement depends on the subscriber category and current NPS exit regulations.
Retirement-focused structure.
Market-linked investment exposure.
Choice of investment allocation under applicable rules.
Potential tax benefits subject to eligibility.
Access to pension-oriented exit arrangements.
Investment returns fluctuate.
Withdrawals and exits are subject to regulatory conditions.
Annuity purchases, where applicable, can affect access to the corpus.
Investors should review current NPS exit and tax rules before making decisions.
Mutual funds are commonly used for long-term wealth accumulation.
They pool investors' money and invest according to the scheme's investment objective.
Different categories may invest in equities, debt securities or combinations of asset classes.
Equity-oriented funds primarily invest in shares of companies.
They may be considered for long-term retirement accumulation by investors who can tolerate market volatility.
However, equity investments can experience substantial declines, and long holding periods do not guarantee positive returns.
Debt funds invest primarily in fixed-income securities.
Their risks can include interest-rate movements, credit deterioration and liquidity constraints.
They should not be treated as equivalent to guaranteed-return deposits.
Hybrid funds combine different asset classes according to their investment mandate.
They may offer a diversified structure, although their risk depends on the allocation and underlying holdings.
A Systematic Investment Plan allows investors to contribute a predetermined amount to a mutual fund at regular intervals.
It can be useful for investors who prefer gradual accumulation rather than investing a large amount at once.
Suppose an investor contributes:
₹5,000 per month
For 20 years:
₹5,000 × 12 × 20 = ₹12,00,000
This represents the total amount invested.
The eventual corpus will depend on market performance, fund expenses and other applicable factors.
A SIP does not guarantee returns or eliminate market risk.
The Senior Citizens' Savings Scheme is a government-backed savings product designed for eligible senior citizens and certain qualifying retirees.
It can form part of a retirement income strategy.
Eligibility based on age and other applicable conditions.
Available through authorised banks and post offices.
Interest paid at prescribed intervals.
Five-year original tenure with extension provisions.
Government-notified interest rate.
Investment limits and premature closure conditions apply.
SCSS can provide a relatively predictable stream of interest income for eligible retirees.
Interest income is generally taxable according to applicable law, and the scheme has restrictions relating to investment limits and early closure.
Fixed deposits are widely used by retirees who prefer a defined interest rate for a specified tenure.
Banks offer deposits with different maturities and payout frequencies.
Some banks provide preferential rates for eligible senior citizens.
Predictable contractual interest.
Choice of tenure.
Periodic interest payout options.
Familiar and relatively straightforward product structure.
Interest income may be taxable.
Early withdrawal can attract penalties.
Reinvestment rates may be lower at maturity.
Inflation can reduce purchasing power.
Bank deposit insurance is subject to the applicable DICGC coverage limit and conditions; not every deposit is fully insured regardless of amount.
Eligible post office savings products can provide additional fixed-income choices.
One example is the Post Office Monthly Income Scheme.
This scheme is designed to provide periodic interest income subject to its investment limits, tenure and other conditions.
The applicable interest rate is notified by the government and may change for new investments.
Government-backed structure.
Periodic income.
Defined scheme terms.
Investment ceilings.
Premature closure conditions.
Taxable interest, where applicable.
Potentially limited protection against long-term inflation.
Government securities can be considered as part of a retirement-oriented fixed-income allocation.
They include securities issued by the Central Government and State Governments under the relevant framework.
Sovereign credit backing for eligible government securities.
Different maturities.
Coupon-based income for applicable bonds.
Opportunity to structure a maturity ladder.
Government securities can experience market-price fluctuations before maturity.
Longer-duration bonds can be particularly sensitive to interest-rate changes.
Investors who sell before maturity may receive more or less than the purchase price.
Floating-rate savings bonds can provide interest income linked to a periodically reset benchmark under the applicable product terms.
Interest rates can change over time.
Specified tenure and interest payment rules.
Premature redemption subject to eligibility and conditions.
Tax treatment according to prevailing law.
These products may appeal to investors seeking government-backed fixed-income exposure, but liquidity restrictions should be understood.
An annuity is a financial arrangement under which an investor pays a premium or lump sum in exchange for payments according to the contract.
Depending on the product, payments may continue for a fixed period or for the annuitant's lifetime.
Payments generally begin soon after the annuity is purchased, according to the policy terms.
Payments begin at a later specified date.
Certain products provide continuing payments to an eligible spouse or second annuitant according to the contract.
Annuities may help create a predictable income stream.
Limited flexibility after purchase.
Inflation may reduce the purchasing power of fixed payments.
Return-of-purchase-price options may affect payout rates.
Taxation and benefits depend on the contract.
Some investors include direct shares in their long-term retirement portfolios.
Equities provide ownership in listed companies and potential participation in business growth.
However, they also expose investors to company-specific and market risks.
Direct ownership in selected companies.
Potential capital appreciation.
Possible dividend income.
Control over security selection.
Significant price volatility.
Permanent capital loss.
Company-specific events.
Corporate governance concerns.
Dividend reductions or suspension.
Portfolio concentration.
Direct equity requires research, monitoring and appropriate diversification.
| Investment Option | Return Structure | Main Risk or Limitation | Potential Role |
|---|---|---|---|
| EPF | Notified interest | Withdrawal restrictions and rule changes | Salaried retirement accumulation |
| PPF | Government-notified interest | Long tenure and liquidity restrictions | Long-term savings |
| NPS | Market-linked | Investment and exit-related risks | Retirement corpus accumulation |
| Equity mutual funds | Market-linked | Equity market volatility | Long-term growth allocation |
| Debt mutual funds | Market-linked | Credit, interest-rate and liquidity risk | Fixed-income allocation |
| SCSS | Government-notified interest | Eligibility and investment limits | Retirement interest income |
| Bank FDs | Contractual interest | Inflation, reinvestment and bank exposure | Capital preservation and income |
| Post office income schemes | Government-notified interest | Liquidity and investment limits | Periodic income |
| Government bonds | Coupon and market-price movements | Interest-rate and liquidity risk | Fixed-income diversification |
| Annuities | Contractual payments | Limited flexibility and inflation | Retirement cash flow |
| Direct equities | Market-linked | Company-specific and market risk | Long-term growth exposure |
No single option is automatically best for every investor.
Retirement planning begins by estimating future living expenses.
A useful starting point is your current monthly expenditure.
However, current expenses should be adjusted for inflation and expected changes in lifestyle.
Suppose your household expenses are currently:
₹40,000 per month
Assume inflation averages 6% annually for illustration.
After 20 years, estimated monthly expenses would be:
Future Expense = Current Expense × (1 + Inflation Rate)^Years
₹40,000 × (1.06)^20 ≈ ₹1,28,285 per month
This means an expense level of ₹40,000 today could require approximately ₹1.28 lakh per month after 20 years under the stated assumption.
Actual inflation will vary and may differ across household spending categories.
| Years From Today | Monthly Expense at 6% Assumed Inflation |
|---|---|
| Today | ₹40,000 |
| 5 years | ₹53,529 |
| 10 years | ₹71,634 |
| 15 years | ₹95,862 |
| 20 years | ₹1,28,285 |
| 25 years | ₹1,71,675 |
These are mathematical illustrations, not forecasts of actual inflation.
A simplified approach is to estimate annual retirement expenses and multiply them by an assumed number of years or a planning multiple.
Suppose your expected annual expenses at retirement are:
₹12,00,000
If you use a preliminary multiple of 25:
₹12,00,000 × 25 = ₹3,00,00,000
This gives a starting estimate of ₹3 crore.
However, the 25-times approach is only a rough planning heuristic. It does not guarantee that the corpus will last throughout retirement.
A more detailed calculation should consider:
Expected retirement age.
Life expectancy and longevity risk.
Inflation.
Healthcare expenses.
Taxes.
Investment returns.
Asset allocation.
Pension and rental income.
Unexpected expenditure.
Withdrawal sequence and market downturns.
Starting earlier can provide more time for investment growth.
Consider two hypothetical investors.
Investor A starts at age 25.
Investor B starts at age 35.
Both invest ₹5,000 monthly until age 60.
Investor A contributes for 35 years, while Investor B contributes for 25 years.
Assuming a hypothetical 10% annual return with monthly compounding, their approximate outcomes are:
| Particulars | Investor A | Investor B |
|---|---|---|
| Starting age | 25 | 35 |
| Retirement age | 60 | 60 |
| Monthly contribution | ₹5,000 | ₹5,000 |
| Investment period | 35 years | 25 years |
| Total contributions | ₹21 lakh | ₹15 lakh |
| Illustrative corpus | ₹1.90 crore | ₹66.3 lakh |
The figures assume monthly investments at the end of each month and a constant nominal return, purely for illustration.
Actual mutual fund or market-linked investment returns will fluctuate and are not guaranteed.
Investors in the early stages of their careers generally have more time before retirement.
This can provide greater flexibility to consider growth-oriented investments, subject to risk capacity.
Important considerations include:
Starting regular savings.
Building an emergency fund.
Managing high-cost debt.
Maintaining suitable insurance.
Establishing long-term asset allocation.
Increasing contributions as income grows.
During the 40s, investors may face multiple financial responsibilities, including education expenses, housing loans and family obligations.
Retirement planning should become more structured.
Useful steps include:
Estimating the required corpus.
Reviewing existing retirement assets.
Increasing savings where affordable.
Assessing portfolio diversification.
Monitoring investment costs.
Reviewing insurance and emergency reserves.
As retirement approaches, the focus often shifts toward balancing growth and capital preservation.
Investors may need to assess:
Expected retirement date.
Pension eligibility.
Debt obligations.
Liquidity requirements.
Healthcare costs.
Portfolio volatility.
Planned withdrawal arrangements.
A gradual and well-considered adjustment may be preferable to making large portfolio changes based solely on short-term market movements.
After retirement, the main objective often changes from accumulation to managing withdrawals and income.
A retiree may need to balance three broad requirements:
Money for near-term expenses and emergencies.
Assets that provide interest, pension, annuity payments or other regular cash flows.
A suitable allocation intended to help manage inflation over a potentially long retirement period.
The appropriate allocation depends on individual circumstances rather than a universal formula.
A Systematic Withdrawal Plan allows an investor to redeem a predetermined amount from a mutual fund at regular intervals, subject to scheme terms.
For example, an investor may request a monthly withdrawal of ₹20,000.
The required number of mutual fund units is redeemed according to the applicable NAV.
No.
SWP payments are funded through redemption of mutual fund units.
If the portfolio experiences poor returns or withdrawals are too high, the investment corpus may decline significantly or eventually be exhausted.
SWPs should therefore not be treated as guaranteed pension products.
A retirement corpus is the accumulated pool of assets available to support future expenses.
Retirement income is the cash flow received or withdrawn from those assets.
For example:
A retiree may have a corpus of ₹1 crore.
That does not automatically mean the corpus can safely generate ₹50,000 every month for life.
The sustainability of withdrawals depends on investment returns, inflation, taxes, longevity and market conditions.
A retirement income strategy should therefore be designed around both current cash flow and long-term capital sustainability.
Estimate when regular employment or business income may stop.
Include household costs, healthcare, insurance, travel and other lifestyle requirements.
Review EPF, PPF, NPS, mutual funds, deposits and other accumulated savings.
Compare your projected retirement requirement with your existing assets and expected future contributions.
Balance growth, capital preservation, income and liquidity according to your circumstances.
Tax treatment can affect the net income and corpus available for retirement.
Review the plan periodically and make adjustments when income, expenses, goals or regulations change.
Delaying contributions reduces the time available for investment accumulation.
Using today's expenses without adjustment can substantially underestimate future needs.
Concentrating retirement savings in one asset or product can increase risk.
A large market decline close to retirement may affect the ability to fund planned withdrawals.
An excessively conservative allocation may struggle to maintain purchasing power over a long retirement.
Medical costs can materially affect retirement budgets.
Market-linked investments do not provide guaranteed returns.
Interest income, pension income, annuity payments and investment redemptions may have different tax implications.
Large withdrawals early in retirement can increase the risk of exhausting savings.
Before finalising a retirement plan, consider:
What age do I expect to retire?
How many years might retirement last?
What are my current monthly expenses?
How much could those expenses increase?
What retirement savings have I already accumulated?
What regular income might I receive after retirement?
How much can I invest each month?
How much investment risk can I tolerate?
How will I meet healthcare expenses?
How much emergency liquidity will I maintain?
How will taxes affect retirement income?
How often will I review the plan?
Retirement planning is not simply about choosing the investment with the highest expected return.
It is about creating a financial structure that can support living expenses, manage uncertainty and provide sufficient flexibility throughout retirement.
Products such as EPF, PPF, NPS, mutual funds, SCSS, fixed deposits, government securities and annuities can serve different purposes within that structure.
Growth-oriented investments may help accumulate wealth during working years, while suitable fixed-income and income-oriented products may become increasingly relevant as retirement approaches.
However, every investment has its own risks, limitations, tax treatment and liquidity conditions.
A well-considered retirement strategy should account for inflation, longevity, healthcare needs, investment risk and sustainable withdrawals.
The earlier retirement planning begins, the more time investors generally have to evaluate options and build a suitable financial foundation.
Common options include EPF, PPF, NPS, mutual funds, SCSS, fixed deposits, government securities and annuity products. The appropriate combination depends on age, goals, risk capacity and income needs.
Begin by estimating retirement age, future expenses, existing savings and the amount you can contribute regularly. Then evaluate suitable investments and asset allocation.
NPS is specifically designed for retirement accumulation, but it is market-linked and subject to applicable contribution, exit and tax rules.
PPF can form part of a long-term retirement savings strategy because of its government-backed structure, but its liquidity restrictions and interest-rate characteristics should be considered.
Yes. Mutual funds can be used for retirement accumulation or planned withdrawals, subject to market risk and scheme-specific conditions.
Fixed deposits provide contractual interest, but investors should consider bank exposure, applicable deposit insurance limits, inflation, taxation and reinvestment risk.
The Senior Citizens' Savings Scheme is a government-backed savings product available to eligible senior citizens and certain qualifying retirees, with interest and tenure governed by scheme rules.
The required corpus depends on expected expenses, inflation, retirement duration, investment returns, taxes and other sources of income. There is no universal amount.
That depends on your monthly expenses, age, expected retirement duration, other income sources and investment performance. A ₹1 crore corpus may be sufficient for some circumstances and inadequate for others.
NPS is a retirement-oriented pension framework with specific regulatory and exit rules, while mutual funds offer a wider range of investment objectives and liquidity structures.
A Systematic Withdrawal Plan allows periodic redemption of mutual fund units. It can support planned cash flow but does not guarantee lifelong income.
Inflation increases future living costs and reduces the purchasing power of fixed income and accumulated savings.
What are the best retirement investment options in India?
How can I start retirement planning?
Which is better for retirement: NPS or PPF?
Can mutual funds be used for retirement planning?
What is the Senior Citizens' Savings Scheme?
How much retirement corpus do I need in India?
Are fixed deposits suitable for retirement income?
What is a Systematic Withdrawal Plan?
Can I retire with ₹1 crore in India?
Why is inflation important for retirement planning?
How should asset allocation change before retirement?
What are the most common retirement planning mistakes?